Electric motorcycles can help commercial riders spend less on fuel and maintenance, but there is a challenge that comes before any of these: getting the bike in the first place.
For many riders, paying the full purchase price upfront is difficult. Fortunately, there are a couple of financing models that spread that cost over time, making it possible for riders to start using an e-bike, earn with it and pay towards ownership along the way.
What it costs to own an e-bike
When comparing an electric motorcycle with a petrol bike, there are two different costs to think about: what it costs to buy the bike, and what it costs to keep using it.
The first can favour petrol. A 2024 Kenyan case study found an estimated cash purchase price of about US$2,050 for an electric motorcycle compared with US$1,140 for a conventional 150cc petrol bike. For a commercial rider earning and spending money day by day, that difference can put an electric motorcycle out of reach even when the longer-term economics look attractive.
Once the motorcycles are on the road, however, the calculation begins to change. Electric motorcycles do not require petrol and avoid several routine engine-maintenance costs associated with petrol bikes. For riders covering long distances every day, those recurring savings can add up.
That is why upfront affordability matters so much. A rider can understand that an e-bike may cost less to operate over time and still be unable to benefit from those savings because they cannot raise the purchase price today.
Financing provides another way to get onto the bike.
Asset financing models for e-bikes
Asset financing simply means gaining access to an asset without having to pay its entire purchase price at once. Instead, another party finances or owns the asset while the customer pays for its use or ownership over time. For a commercial rider, the asset is not only something to own; it is also something that can immediately be used to generate income.
There are several ways this can work with motorcycles.
The models solve the same basic problem in different ways: reducing the amount of money a rider needs before they can start using the motorcycle.
What changes is how much is required upfront, how frequently payments are made, what information is required to qualify, who owns the bike during the agreement and what happens if the rider can no longer continue paying.
For commercial riders, those differences matter because income does not always arrive like a salary at the end of the month.
Traditional motorcycle loans vs M-KOPA’s pay-as-you-go financing
A traditional motorcycle loan (or asset loan) is usually provided by banks and other financial institutions. They help riders finance motorcycles by lending part of the purchase price and allowing the borrower to repay over time.
For example, KCB's Boda Boda/Tuktuk Loan currently requires a 10% customer contribution and allows repayment over as long as 24 months for motorcycles. The motorcycle being purchased serves as security for the loan.
That model can work well for riders who meet the lender's requirements.
Newer pay-as-you-go models approach affordability differently. They are often designed specifically around customers whose income may be informal, variable or received daily, and the repayment structure can reflect that reality more closely.
At M-KOPA, we use pay-as-you-go financing to help eligible riders access electric motorcycles without first having to save the full purchase price. Through M-KOPA Mobility, riders can access electric motorcycles and start using them as productive assets while paying towards ownership over time. Our model is designed around Every Day Earners, including commercial riders whose income may be earned one trip at a time rather than through a monthly salary.
Here is how a conventional motorcycle loan compares with the model we use for e-bike ownership at M-KOPA:
How we make e-bikes more accessible at M-KOPA
We currently work with electric-motorcycle partners including Roam, Ampersand and Spiro, giving riders access to different models and energy options depending on how and where they work.
The goal is straightforward: reduce the gap between a rider wanting an income-generating e-bike and being financially able to start using one. So instead of saving until you can afford the full cost before you can buy the e-bike and start working with it, our financing model allows you to make the required initial payment, get the e-bike, and start working and earning while you make payments in installments, and earn more from lower running costs.
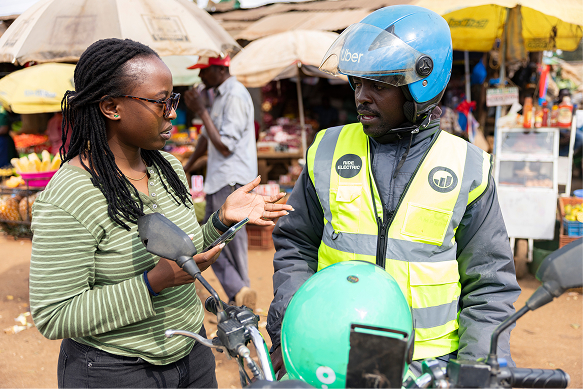
Kenyan entrepreneur Mary Atieno Oketch offers one example. She accessed a Roam Air with a KSh25,000 initial payment and KSh550 daily instalments. She then hired a boda boda rider to use the motorcycle, allowing the asset to begin generating income while she continued paying towards it.
Why financing matters for riders
The importance of financing becomes clearer when we look at what happens after riders get onto the road. By November 2025, we had financed more than 5,000 electric motorcycles in Kenya. Our Kenya impact findings showed that riders were saving an average of KSh730 per day through lower fuel spending, fewer repairs and efficient battery swapping, while 66% reported earning more after moving to electric mobility.
Those benefits help explain why financing matters to e-bike adoption.
It can help riders:
- Own an e-bike sooner.
- Start earning with the asset while paying for it.
- Access electric-mobility savings earlier.
- Match payments more closely to how they earn.
- Keep more capital available for other needs.
- Turn affordability into ownership.
The long-term economics of an electric motorcycle may already make sense on paper. But a rider cannot benefit from cheaper energy, lower maintenance or higher take-home income until they can actually access the bike.
Device financing helps bring those benefits forward. That is why wider e-bike adoption will depend on more than just manufacturing more electric motorcycles. Riders also need reliable charging or battery-swapping infrastructure, servicing, suitable bikes and financing structures that reflect how they actually earn and work.
When those pieces come together, switching to electric becomes less of a future possibility and more of a practical decision a rider can make today.
Ready to see what going electric could mean for you?
For a commercial rider, choosing an e-bike is ultimately about more than the purchase price. It is about what the bike costs to access, what it costs to keep on the road and how much of each day's earnings it allows you to keep.
With M-KOPA Mobility, eligible riders can access an electric motorcycle through flexible pay-as-you-go financing and start putting the bike to work while paying towards ownership.
Explore M-KOPA Mobility and find an e-bike that works for you.