According to the GSMA’s 2024 research on smartphone adoption in Africa, affordability remains the biggest reason smartphone adoption on the continent has not kept pace with network coverage. Across Sub-Saharan Africa, an entry-level smartphone cost about $39 in 2024, equivalent to 26% of average monthly income, but the burden rose to 64% for the poorest 40% of the population and 87% for the poorest 20%.
Nigeria, Kenya and South Africa show just how differently that problem can play out. Their smartphone prices, income levels and financing markets vary considerably, yet they lead us towards the same conclusion: for many Every Day Earners, the biggest obstacle is not simply the total price of the phone. It is having to find all that money at once.
That is where pay-as-you-go becomes important.
The price tag is only half the story
If you walk into a shop to buy a smartphone, the price displayed on the shelf tells you what the phone costs. It does not tell you what that amount means to the person expected to pay it. The GSMA’s 2024 affordability data makes this especially clear. An entry-level smartphone in Nigeria costs around $18, compared with $39 in Kenya and just $13 in South Africa. But once those prices are compared with people's monthly incomes, the picture changes completely.
For someone in Nigeria's poorest 20%, therefore, an $18 entry-level smartphone was equivalent to 73% of their monthly income. In Kenya, the $39 phone represented 67% of monthly income for the same income group. South Africa was considerably better at 15%, but even that is very different from the 3% suggested by the national average. So when we say that a smartphone costs $18, $39 or $13, we have not yet answered the most useful question, which is: how difficult is it for the person who needs that phone to buy it?
Let’s take a detailed look at the cost of smartphone ownership in these countries.
Nigeria
Nigeria is perhaps the clearest example of why a low smartphone price does not automatically mean high affordability. The country's median entry-level smartphone price fell dramatically from $84 in 2018 to just $18 in 2024. Yet the same GSMA smartphone adoption analysis of Nigeria found that the smartphone still represented 26% of average monthly income, rising to 56% for the poorest 40% of Nigerians and 73% for the poorest 20%.
Think about what 73% of a month's income means in practical terms. A person still needs to eat, travel to work, pay rent, support a family, buy stock for a business or deal with whatever unexpected expense appears that month. The real question is whether they can set aside that much money at once without sacrificing other essential expenses..
That challenge has become even more difficult as currency depreciation and rising living costs have reduced some of the affordability gains created by cheaper devices. GSMA's research notes that although smartphone prices have fallen considerably in Nigeria over the longer term, worsening economic conditions have continued to put pressure on what households can actually afford.
This also helps explain why financing matters. If an Every Day Earner can afford to put aside a smaller amount from today's earnings, another amount tomorrow and another next week, the problem is not necessarily their ability to pay for the device over time. The problem may simply be the demand to produce the entire amount before they are allowed to start using it.
Kenya
Kenya has one of Africa's most developed mobile-money markets and is no stranger to device financing, yet smartphone affordability remains a major issue. In 2024, the country's median entry-level smartphone cost $39, equivalent to 20% of average monthly income. For the poorest 40% of Kenyans, that rose to 50%, while someone in the poorest 20% would need the equivalent of 67% of their monthly income to buy a phone.
This helps explain why mobile phone cost remains such a prominent barrier to getting online. The newer GSMA Mobile Gender Gap research, for instance, shows that phone affordability continues to be one of the most frequently cited barriers to mobile-internet adoption among both Kenyan men and women.
Kenya has already demonstrated that spreading payments can help. Device-financing initiatives have allowed customers to break smartphone costs into much smaller instalments instead of paying the full purchase price at once. But there is another important lesson here: financing works best when the repayment schedule resembles the customer's income schedule. A shopkeeper may make money every day. A boda boda rider may have good weeks and slower ones. A market trader might make more money around weekends or particular seasons. But can they predict their salary every month, or afford to buy a phone upfront?
This is part of the thinking behind our smartphone financing at M-KOPA for Every Day Earners, where customers can start with an initial payment and make smaller repayments over time rather than waiting until they have accumulated the entire purchase price.
South Africa
South Africa looks very different when we compare the numbers from the smartphone adoption report. Its $13 median entry-level smartphone represented only 3% of average monthly income in 2024. Even for the poorest 20%, the figure was around 15%, substantially lower than Nigeria's 73% and Kenya's 67%.
The government policy on tax reform has also helped. South Africa removed its 9% ad valorem excise duty from smartphones priced below R2,500 in April 2025, explicitly recognising that entry-level smartphones increasingly function more like essential digital tools than luxury goods. The GSMA's subsequent assessment of the tax change found a significant improvement in entry-level smartphone sales after the reform.
The same smartphone adoption research on South Africa shows that the lowest-income groups remain more exposed to device costs, while traditional financing can present another obstacle for people without formal payslips or established credit histories. This matters because a person can have real, consistent economic activity without looking like a conventional salaried borrower. A street vendor might make sales every day but have no payslip. A self-employed mechanic can have customers and income without a long credit history. A small-business owner might turn over money constantly without receiving a neat salary at the end of every month.
The real problem is having to pay upfront
Put the three markets beside one another and something interesting happens. Nigeria has a cheaper entry-level phone than Kenya, yet the phone is harder to afford relative to income. South Africa has significantly better average affordability, but lower-income consumers can still face barriers. And across all three markets, the people who most need financing are often the same people whose incomes do not fit neatly into conventional lending models.
This leads to two very different questions:
- Can I afford this smartphone over time?
- Can I afford the entire smartphone right now?
Those questions sound similar, but for an Every Day Earner they can have very different answers. Suppose a trader earns something every day. Over several months, she may comfortably earn many times the price of a smartphone. If she chooses to save until the full price is available, she also has to protect those savings from every other expense competing for the same money.
Pay-as-you-go changes the cost for an Every Day Earner
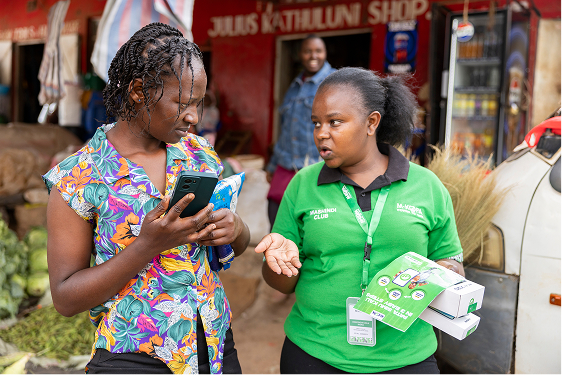
With M-KOPA, eligible customers begin with a smaller initial payment, receive the smartphone and then continue paying in manageable instalments. Our pay-as-you-go model is built around small payments that better match the cash-flow patterns of Every Day Earners, rather than requiring collateral, guarantors or formal credit scores before someone can begin.
This model is inclusive, flexible and progressive because customers get access with a relatively small deposit; repayments are designed around daily cash flows; and those repayments begin building a financial history that can eventually unlock other services. 92% of surveyed M-KOPA customers say the financing makes products more affordable.
For someone who already has enough spare money to buy a smartphone outright, cash may still make perfect sense. The advantage of pay-as-you-go is not that everyone should finance a phone but that people who can afford a phone progressively do not have to be excluded simply because they cannot afford it all at once.
You can start using the phone before you finish paying for it
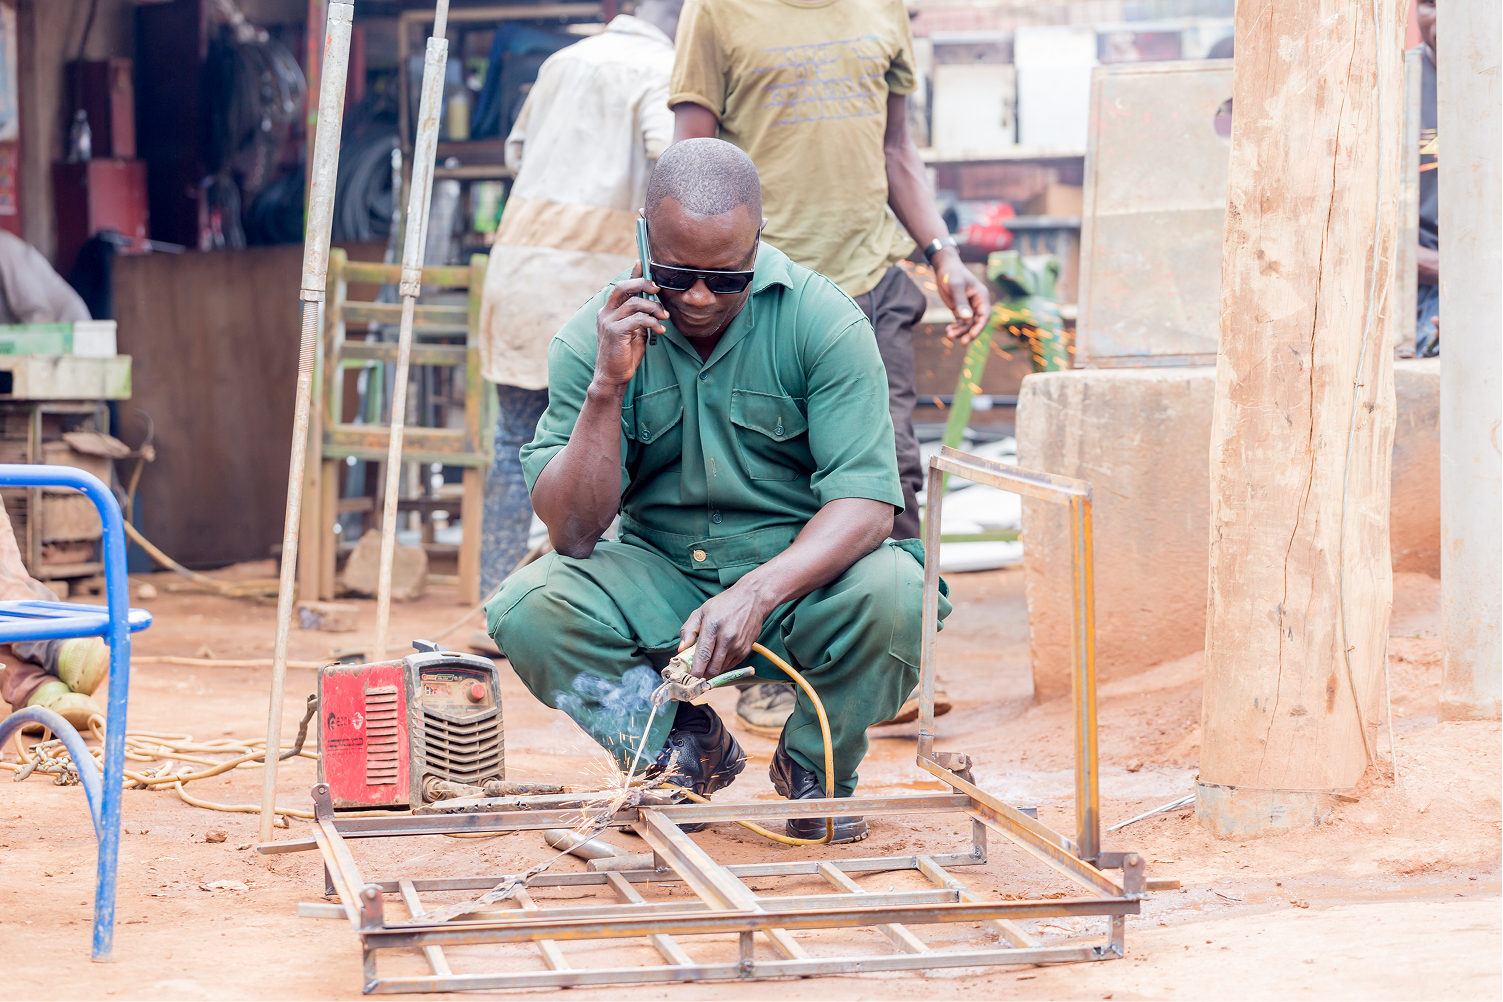
There is another cost we often leave out of smartphone affordability: the cost of waiting. A smartphone is not only something people use for calls, entertainment or social media. For many Every Day Earners, it is increasingly part of how they make money. A trader can post products on WhatsApp, receive customer orders and communicate with suppliers. A rider can navigate, receive work and communicate with customers. Someone looking for work can search and apply online. A small-business owner can advertise without paying for a physical billboard.
Our impact data suggests these uses are already widespread.
Nigeria: 77% of customers use their smartphones or digital loans to generate income, while 75% report earning more since accessing M-KOPA.
Kenya: 67% said they use their M-KOPA product to generate income, while 52% reported earning more.
South Africa: By April 2026, M-KOPA had served more than 105,000 customers and unlocked over R370 million in credit.
For small-business owners specifically, M-KOPA has documented how smartphones are being used to reach customers, take orders and keep money available for stock rather than using a large lump sum to purchase a device. Our success stories from Kenyan and South African business owners make that relationship between device accessibility and everyday commerce particularly tangible.
Why pay-as-you-go wins
As you’ve seen, the smartphone affordability challenge looks different in Nigeria, Kenya and South Africa. But the good thing is, for these three different markets, many consumers can afford a smartphone progressively even when they cannot pay the full cost upfront.. This is particularly important for Every Day Earners across these countries, because their economic lives are not necessarily organised around a monthly salary. They may earn daily, weekly or whenever customers come.
A financing model built around those realities can make a device accessible regardless of when they earn. This is one reason our financing model at M-KOPA has grown so quickly. In July 2026, we reached 10 million customers across 5 African markets, having added 9 million customers in the 6 years since entering smartphone financing. That scale does not mean pay-as-you-go will be the right purchasing method for every person, but it is strong evidence that millions of people need another route to ownership besides upfront payment.
Conclusion
There is still enormous value in making smartphones cheaper, but price reduction alone cannot solve every affordability problem. However, with pay-as-you-go, a customer can turn one large payment into a series of manageable ones, start using the smartphone sooner and, where that device supports work or business, begin benefiting from it while they are still paying towards ownership.
For millions of Every Day Earners, real affordability can begin when the cost of the phone starts moving at the same pace as the money they earn.
Join other M-KOPA customers today. Get your smartphone and unlock other benefits.