A digital loan can be used to restock a shop, buy equipment, pay school fees or deal with an emergency. The money may come from the same place, but whether borrowing is a good decision depends heavily on what you intend to do with the money.
Business or Personal?
The biggest difference is simple: a business loan should ideally help you make or protect money, while a personal loan usually has to be repaid from money you are already earning. That means the two should be judged differently.
Let’s examine them further.
Business loans vs personal loans
Digital loans are not always formally labelled “business” or “personal”, and a research on digital credit shows that borrowers commonly use the same products for both household and business needs.
What matters is the purpose.
If you borrow KSh20,000 to buy stock that generates KSh30,000, the loan has the potential to help create additional income. If you borrow KSh20,000 for rent, the rent may be important, but it does not generate the money needed to repay the loan.
That difference determines how you should evaluate the borrowing.
Consider ROI for business loans
Return on investment (ROI) is a simple way to estimate how much money you make back from the money you put into your business. So, before putting borrowed money into a business, you should have some idea of what that money is expected to produce. You do not need complicated accounting software to make a useful estimate. These three calculations below are a good place to start.
1. Net gain after borrowing costs
Calculate what the business is expected to make after paying the interest and fees attached to the loan.
Additional business profit – interest and fees = net gain from the loan
If a KSh20,000 loan helps generate KSh10,000 in additional profit and borrowing costs KSh2,000, the real gain created after financing is KSh8,000.
2. Return on borrowed capital
You can then compare that gain with the amount you borrowed:
Net gain ÷ amount borrowed × 100 = ROI
Using the example above: KSh8,000 ÷ KSh20,000 × 100 = 40% ROI
A positive result does not automatically make the loan a good idea, but it helps you see whether the expected return is large enough to justify the cost and risk of borrowing.
3. Repayment coverage
Profit alone is not enough. You also need to know whether the business will produce cash before the repayment is due. For example, if a tailor takes a profitable order today but will only be paid in six weeks, a loan due in two weeks could still create problems. Before borrowing, compare when the business will receive its money with when the lender expects to be paid.
Whichever calculation you use, work with the full cost of borrowing rather than just the advertised interest rate.
Consider affordability for personal loans
A personal loan needs a different calculation because paying school fees, rent or an urgent medical expense does not normally create a financial return. Instead, ask whether your existing income can absorb the repayment.
If you borrow KSh5,000 today and repaying it next week means you will need another loan to buy food or get to work, the first loan may have solved one problem by creating another.
Before taking a personal loan, ask yourself:
- What exactly am I borrowing for?
- What income will repay the loan?
- How much will remain after the repayment?
- Can I still meet my essential expenses?
- Would I need another loan if something unexpected happens?
Earlier research into digital borrowing in Kenya and Tanzania found that household expenses were among the most common uses of digital credit, which makes this affordability test particularly important.
Loan risk management: 5 rules to remember
Whether you are borrowing for business or personal use, a few simple habits can reduce the risk of the loan becoming difficult to manage.
- Borrow for a clear purpose: Know what the money is going towards before accepting it. Borrowing for business is particularly risky when you take the money first before deciding how to use it.
- Borrow only what you need: Qualifying for KSh50,000 does not mean you should borrow KSh50,000 if the business opportunity requires only KSh30,000. The extra KSh20,000 still attracts a repayment obligation.
- Match repayment to your cash flow: A loan may be affordable overall but badly timed. Make sure the money you expect to earn becomes available before or around the time repayments are due.
- Plan for a slower month: Do not calculate affordability using only your best week. Ask whether you could still make the payment if sales were lower, a customer paid late or an unexpected expense appeared.
- Avoid borrowing to repay borrowing: Repeatedly taking another digital loan to service an existing one can be an early sign that debt is becoming difficult to manage.
Good risk management is not about avoiding credit altogether. It is about making sure the loan remains a tool you control rather than becoming another expense controlling your income.
M-KOPA success stories with digital loans
We have seen M-KOPA customers use digital credit most successfully when they can connect the loan directly to something productive.
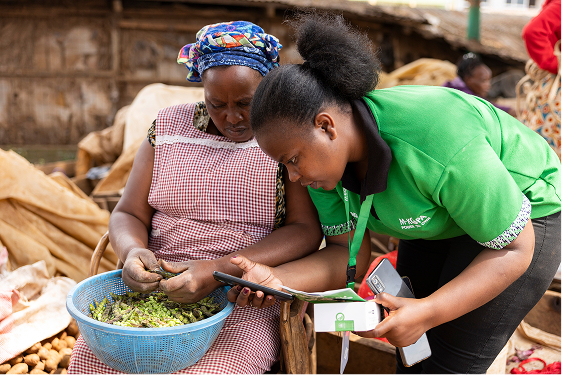
In Kenya, Lydia Wangui Nderitu was selling porridge and using each day’s earnings to buy ingredients for the next. After building a repayment history with M-KOPA, she became eligible for a KSh7,000 digital loan that she invested as working capital. That additional capital helped her move from hawking porridge to operating from a physical location in Makina market and making deliveries to customers.
In Uganda, Susan Talengera used a UGX500,000 M-KOPA cash loan to buy a larger mixer for her bakery and additional stock for her drug shop. Rather than borrowing without a plan, the money went directly into equipment and inventory that could strengthen businesses she was already running.
The common lesson is not simply that both customers received credit, but that they could identify what the money was going into and how that investment could improve what they were already earning from.
Important Note: At M-KOPA, we create a pathway to formal credit for Every Day Earners who may not meet conventional collateral or guarantor requirements. You can qualify for an M-KOPA digital-loan as you build a repayment history through your smartphone.
Conclusion
Business and personal loans can both be useful, but they should not be judged the same way. A business loan should have a believable path to creating more value than it costs, while a personal loan needs a realistic repayment plan that does not leave your everyday finances under greater pressure.